
Not Just Another Index.
It’s The New Generation.®
We offer specialized solutions for investors seeking exposure to New Listings - a proxy for economic growth and innovation.

Upcoming Global IPOs
Bamboo Insurance Services (Ticker: BMB US) is a U.S. homeowners insurance business that uses technology and AI to help price policies, assess risk and manage claims. The company operates as a managing general underwriter (MGU), meaning it handles much of the insurance process while partner insurance carriers provide the capital and ultimately bear the claims risk.
Bamboo, which is incorporated in Delaware and backed by CVC, plans to list on the New York Stock Exchange on September 23, 2026. Selling shareholders are offering 35 million shares at $18.00 to $20.00 each, implying proceeds of approximately $665 million at the midpoint and up to $700 million at the top of the range. The offering implies an estimated market capitalization of around $3.0 billion, while Reuters reported a fully diluted valuation of up to approximately $3.2 billion.
All shares in the IPO are being sold by existing shareholders, so Bamboo itself will not receive any proceeds from the offering. J.P. Morgan, Morgan Stanley, Deutsche Bank Securities, Evercore ISI and Wells Fargo Securities are managing the IPO.
ADARx Pharmaceuticals Inc. (Ticker: ADRX US) is a U.S. late-stage biotechnology company developing RNA-targeted therapeutics across complement-mediated, genetic, cardiovascular, thrombosis, central nervous system and metabolic diseases, including obesity. The company has developed technologies designed to selectively control the expression of disease-related targets and is advancing a pipeline of RNA therapeutic candidates. ADARx also has a collaboration and license option agreement with AbbVie covering siRNA therapeutics across multiple disease areas, including neuroscience, immunology and oncology.
ADARx plans to list on Nasdaq on September 25, 2026, following expected pricing on September 24. The company is offering 21.875 million shares at $15-$17 per share, representing an IPO size of approximately $350 million at the midpoint. The offering consists entirely of primary shares, with proceeds therefore going to the company before fees and expenses. J.P. Morgan, Morgan Stanley, TD Cowen and UBS are acting as bookrunners.
RoboTechnik Intelligent Technology Co., Ltd. (Ticker: 3757 HK) is a Chinese provider of intelligent manufacturing equipment and systems for the photovoltaic (PV) and silicon photonics (SiPh) industries. Its offerings include PV cell automation equipment, complete production lines, intelligent manufacturing systems centered on its R2Fab MES platform, and, through ficonTEC, SiPh assembly and testing equipment.
RoboTechnik plans to list in Hong Kong on September 29, 2026, offering approximately 11.88 million primary shares at HKD 436 per share and raising approximately HKD 5.18 billion (approximately $660 million). The offering includes a 15% greenshoe facility covering approximately 1.78 million additional shares.
According to CIC data cited by the company, RoboTechnik ranked fifth globally in intelligent PV cell automation manufacturing equipment by 2025 revenue, with a 2.6% market share, and first globally in intelligent SiPh manufacturing equipment, with a 20.5% market share. Citigroup Global Markets Asia, Futu Securities International (Hong Kong), and Huatai Financial Holdings (Hong Kong) are among the offering managers.
Red Avenue New Materials Group Co., Ltd. (Ticker: 9607 HK) is a Chinese new materials company engaged in the R&D, production and sale of rubber additives, electronic materials and fully biodegradable materials. Red Avenue, which has been listed on the Shanghai Stock Exchange since 2018, plans to list its H shares on the Hong Kong Stock Exchange on September 29, 2026.
The company plans to offer approximately 68.12 million primary shares at HKD 39.00-44.00 per share, raising up to approximately HKD 3.0 billion (approximately $382 million). Its products include phenolic resins and other rubber additives used in tyres, semiconductor and display photoresists, CMP polishing pads, high-purity solvents and PBAT biodegradable materials.
According to Frost & Sullivan data cited in the prospectus, Red Avenue ranked first globally in phenolic resin rubber additives for tyres by 2025 sales revenue, with a 41.4% market share, and ranked first among local suppliers in China’s semiconductor and TFT-array photoresist markets. The company operates seven production facilities in China and is developing a new rubber-additives production base in Thailand.
Shenzhen Kinwong Electronic Co., Ltd. (Ticker: 3228 HK) is a Chinese printed circuit board (PCB) manufacturer serving automotive electronics, telecommunications and data infrastructure, smart devices, industrial control, AI computing and other markets.
Kinwong plans to list its H shares on the Hong Kong Stock Exchange on September 29, 2026, offering approximately 72.94 million primary shares at HKD 69.88 per share and raising approximately HKD 5.1 billion (approximately $650 million). According to CIC data cited in the prospectus, the company was the world’s largest automotive electronics PCB provider by revenue in 2025, with a 10.6% market share, and ranked eleventh among PCB providers globally with a 2.5% share.
Its products include multilayer, HDI, flexible, high-layer-count and other advanced PCBs used in areas including autonomous driving, AI computing infrastructure and next-generation communications. The company served more than 800 customers across 53 countries or regions during the track record period. CLSA, Guolian Securities International Capital and Merrill Lynch Asia Pacific are managers of the offering.
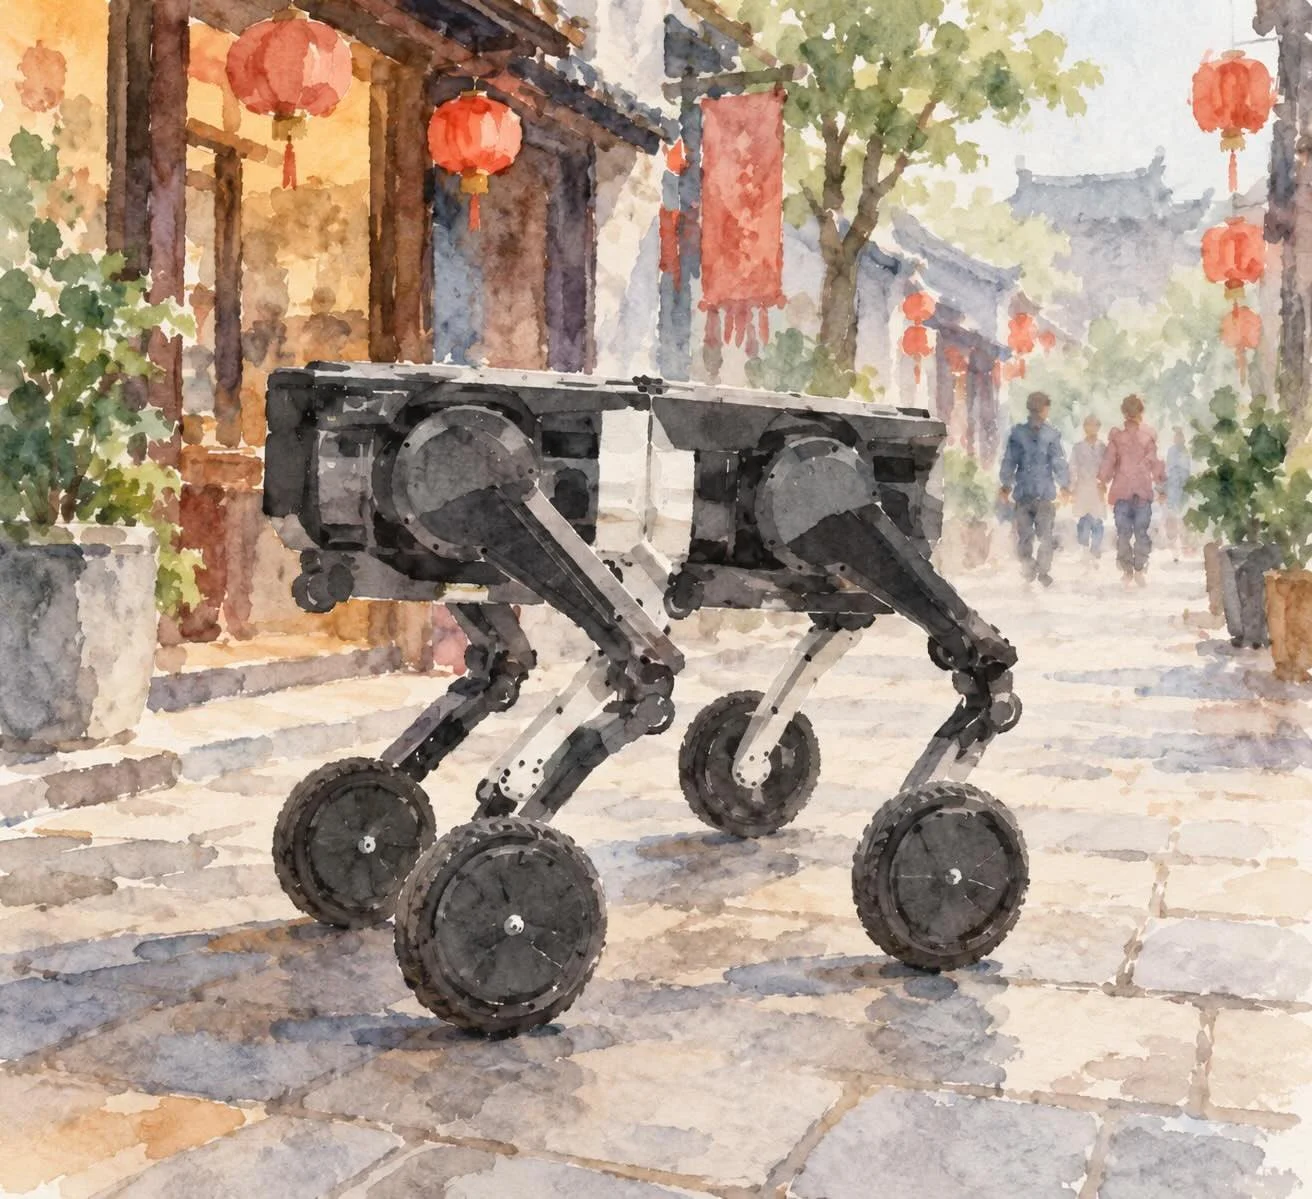
Direct Drive Tech Limited (Ticker: 6731 HK) is a Chinese robotics and precision motion-control company developing and manufacturing direct-drive motors, power modules and robotic systems.
The company plans to list on the Hong Kong Stock Exchange on September 29, 2026, offering 50.00 million primary shares at HKD 21.60 per share and raising approximately HKD 1.1 billion (approximately $138 million). The offering implies a market capitalization of approximately $1.0 billion.
Direct Drive Tech’s product portfolio includes direct-drive robotic platforms such as D1, TITA and DIABLO, as well as related motion-control technologies and robot middleware, with applications including inspection, delivery and other mobile-robotics use cases. The offering includes a 15% greenshoe facility covering 7.50 million additional shares. CLSA, CMB International Capital, China Harbour International Securities, Futu Securities International (Hong Kong) and Neutral Financial Holding are managers of the offering.
Oura Inc. (Ticker: OURA US) is a Finnish-founded health technology company operating a health intelligence platform centered on Oura Ring, a smart ring that tracks more than 50 health metrics, including sleep, activity, stress, readiness, women’s health, metabolic health and heart health. The company serves millions of members globally and also works with research teams, healthcare providers, sports organizations and other partners.
Oura plans to list on Nasdaq on September 30, 2026, following expected pricing on September 29. The company has filed to offer 50 million shares at a price range of $40-$44 per share, representing an offer size of approximately $2.1 billion at the midpoint. Approximately 27% of the shares are primary and 73% are secondary, meaning most of the IPO proceeds are expected to go to selling shareholders rather than the company. J.P. Morgan, Goldman Sachs, Morgan Stanley, Allen & Co. and Jefferies are acting as bookrunners.
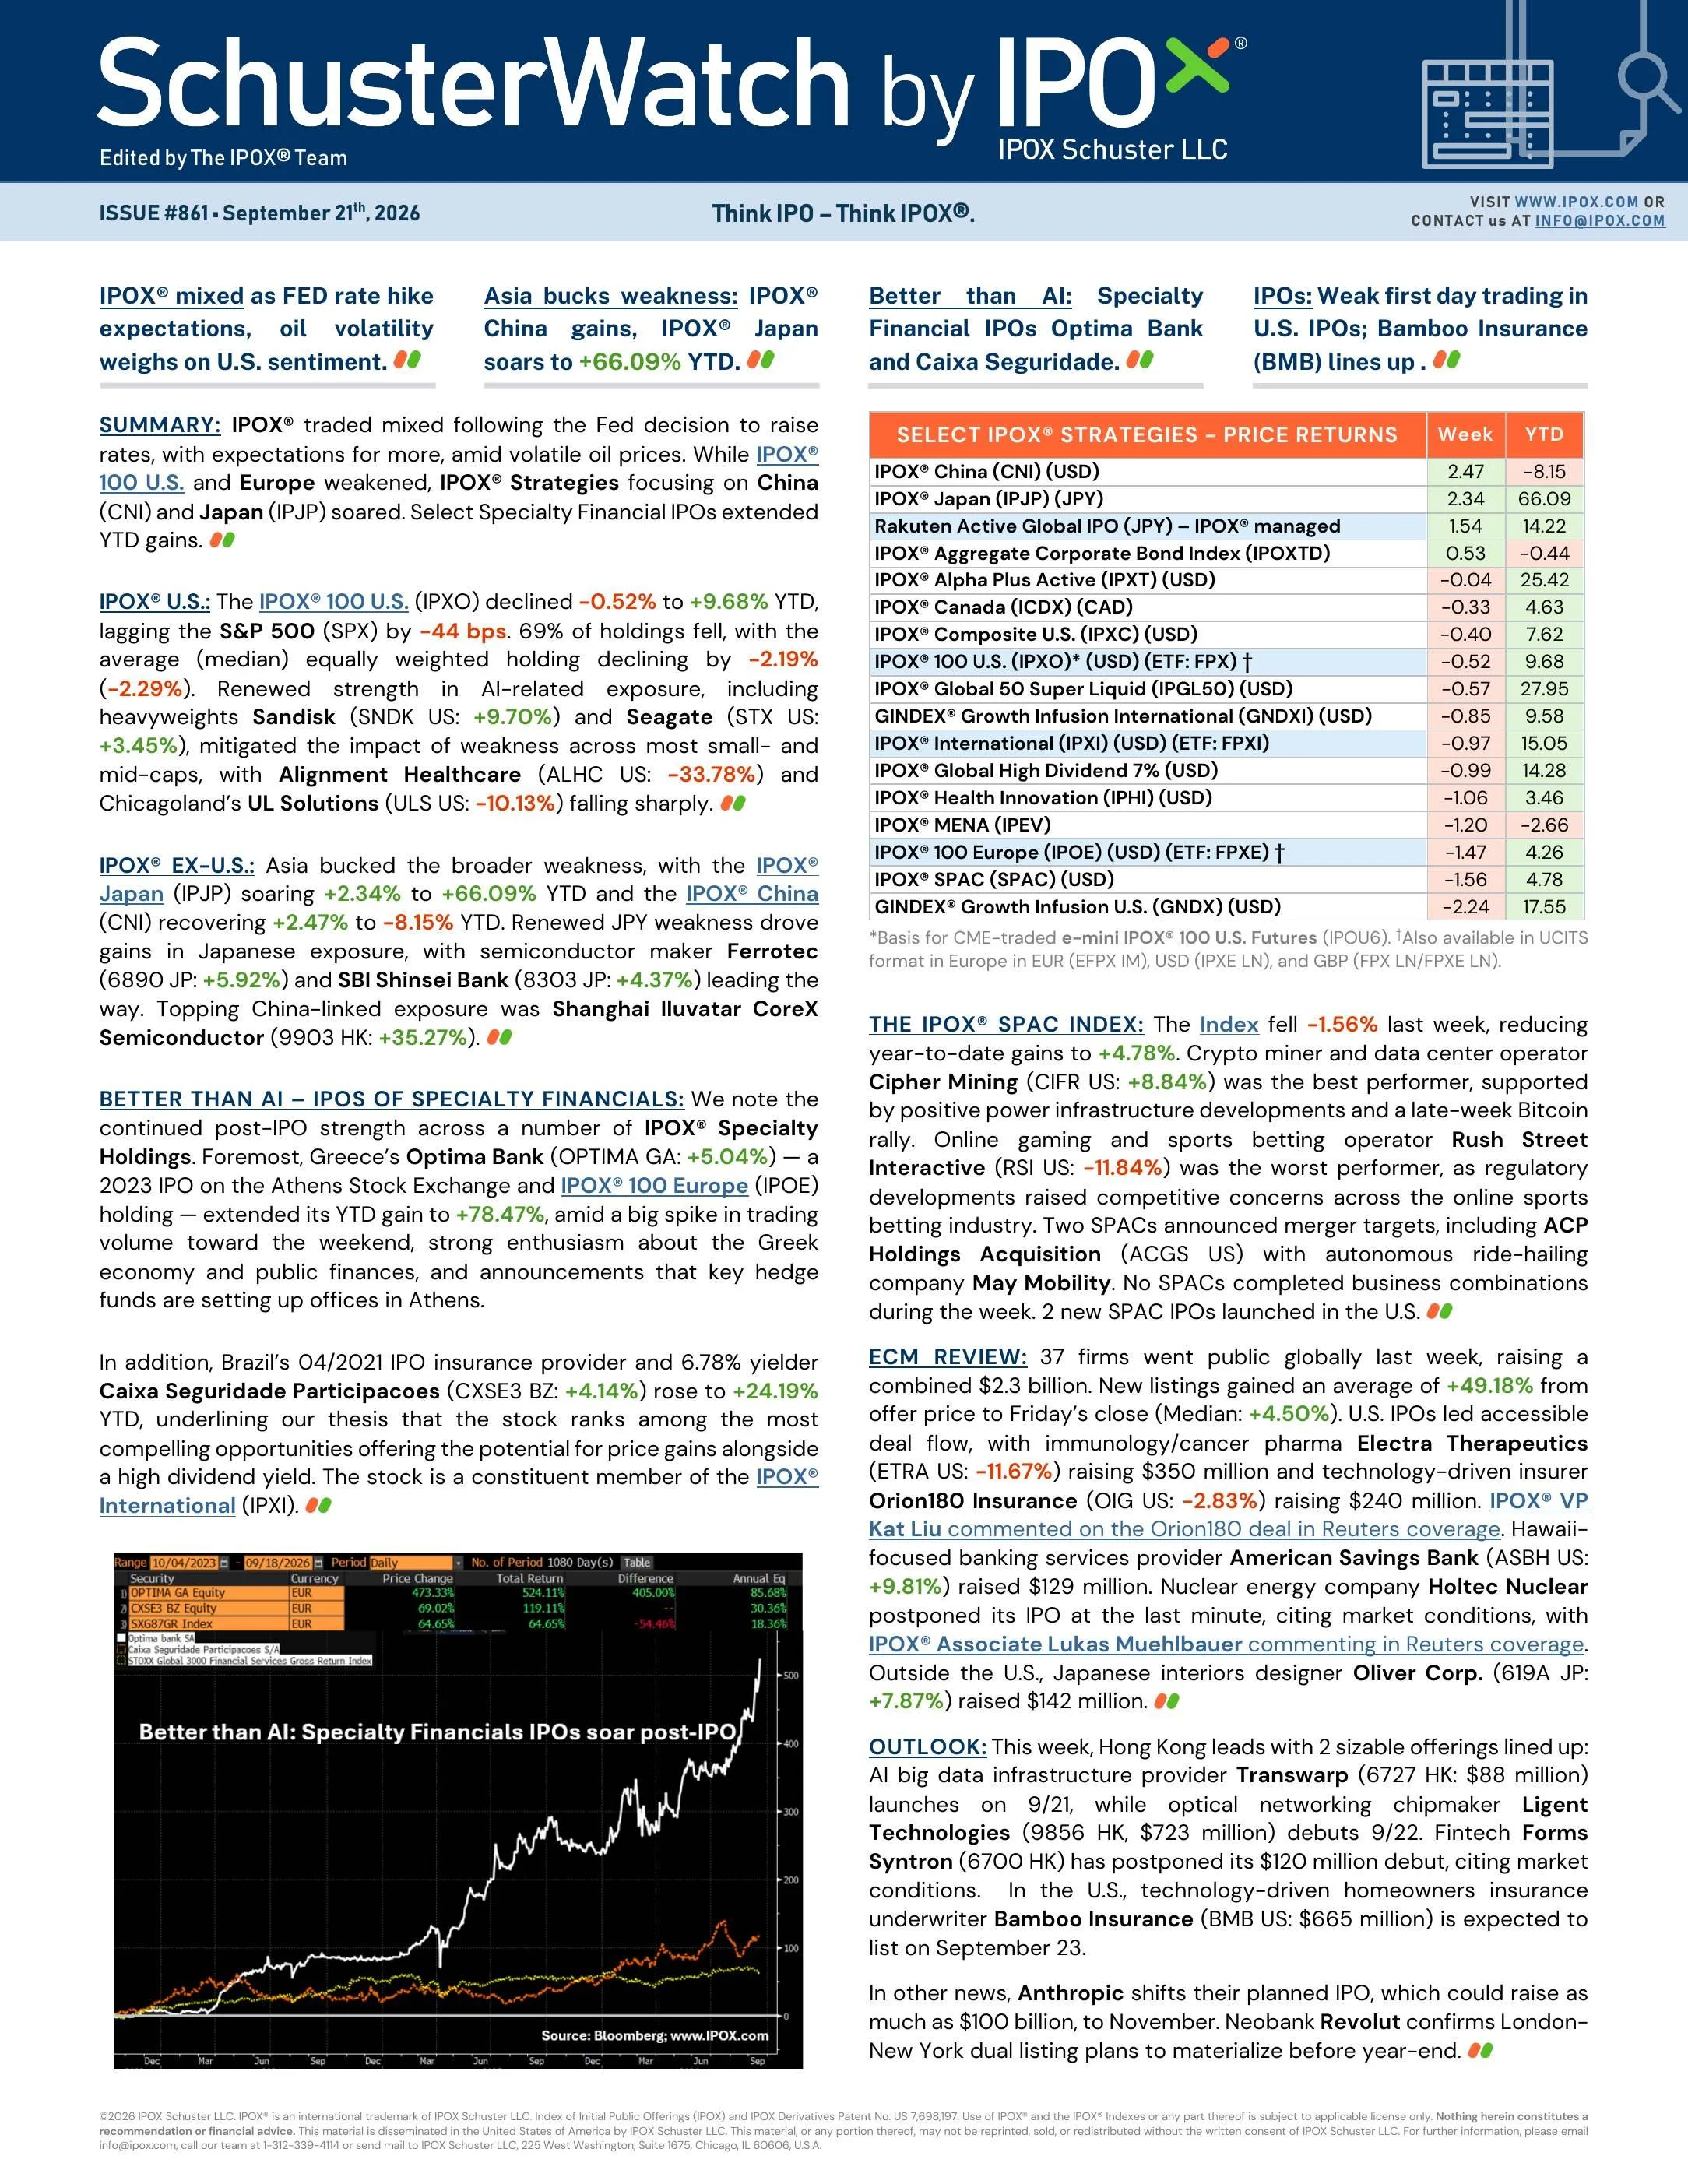


The IPOX® Newsletters
IPOX® in the News
IPOX® VP Kat Liu comments on Oura’s planned U.S. IPO, which targets a fully diluted valuation of about $15.6 billion and could raise up to $2.2 billion. Liu highlighted Oura’s beginner-friendly, fashionable positioning in wearables, while noting that the valuation reflects expectations for continued strong growth and a greater shift toward higher-margin recurring revenue. Oura is expected to price next week and trade on Nasdaq under the ticker OURA, following its fall roadshow launch.
IPOX® VP Kat Liu comments on Oura’s planned U.S. IPO, which targets a fully diluted valuation of about $15.6 billion and could raise up to $2.2 billion. Liu highlighted Oura’s beginner-friendly, fashionable positioning in wearables, while noting that the valuation reflects expectations for continued strong growth and a greater shift toward higher-margin recurring revenue. Oura is expected to price next week and trade on Nasdaq under the ticker OURA, following its fall roadshow launch.

IPOX® VP Kat Liu commented in Reuters on Orion180 Insurance’s Nasdaq debut and the excess and surplus insurance market. Liu explained that E&S carriers serve risks many traditional insurers cannot or do not want to write on standard terms, with greater flexibility in pricing, coverage limits and policy design. She added that Orion180’s opportunity has been accelerated by a cyclical dislocation as larger insurers pull back, rather than depending solely on those market conditions for its growth in the sector.
Reuters cited IPOX® Associate Lukas Muehlbauer on Holtec’s suspended U.S. IPO, linking the company’s investment case to expectations for higher electricity demand from data centres amid the AI boom. Muehlbauer said the broader IPO pipeline should remain active without widespread postponements, while noting investor concerns around AI development, interest rates, and weak nuclear-sector performance. “The underlying demand for energy has not disappeared, but investors are becoming more selective about how much they are willing to pay today for future growth.”
IPOX® Associate Lukas Muehlbauer commented on Altera’s planned U.S. IPO, highlighting investor focus on the chipmaker’s exposure to hyperscalers and AI infrastructure demand. Reuters reported that Altera, backed by Silver Lake and Intel, has confidentially filed to go public and could raise more than $2 billion. Muehlbauer noted that whether hyperscalers remain a material part of Altera’s customer base will be an important consideration for investors once the company’s public filing becomes available.
The IPOX® Update

Global IPO activity this week featured several large planned offerings alongside notable delays. Firmus Technologies is seeking up to $5 billion in Australia, while Bamboo Insurance targets up to $700 million in New York. BASF advanced plans for a major Frankfurt listing, and Revolut and Vue explored future London-linked IPOs. Holtec, Dusk and Forms Syntron postponed or shelved offerings. Other deals included Linjemontage in Stockholm, Wiluna Mining in Australia and RoboTechnik’s $800 million Hong Kong secondary listing during the period.

Global IPO activity is accelerating into the fall, with major prospective listings spanning the U.S., Europe, Asia-Pacific and MENA. Altera leads the pipeline with a potential $2 billion-plus U.S. IPO, while Holtec Nuclear, Stratolaunch and Orion180 advance offerings. Europe features Belron and Ignis, while Asia-Pacific activity includes AirTrunk, Mynt, Musinsa and Transwarp Technology. In MENA, MNT-Halan has begun the Cairo listing process, highlighting broad investor appetite across technology, infrastructure, defense, insurance and fintech as issuance momentum builds toward year-end globally.

U.S. IPO activity is led by SB Energy’s planned $5 billion Nasdaq deal, alongside Cumberland Farms’ pre-IPO financing and Golden Pet Brands’ New York plans. In Europe, Nscale is raising $3.5 billion ahead of a potential flotation, while Blackstone prepares Hotel Investment Partners for a Spanish listing. Asia-Pacific remains especially active, with Moonshot AI, Asia OneHealthcare, Ligent, Club Med, Akulaku, Jollibee’s international unit and VinFast-linked GSM all advancing toward Hong Kong or Malaysian IPOs across technology, healthcare, hospitality and mobility.